Navigating Entrepreneurship While Employed
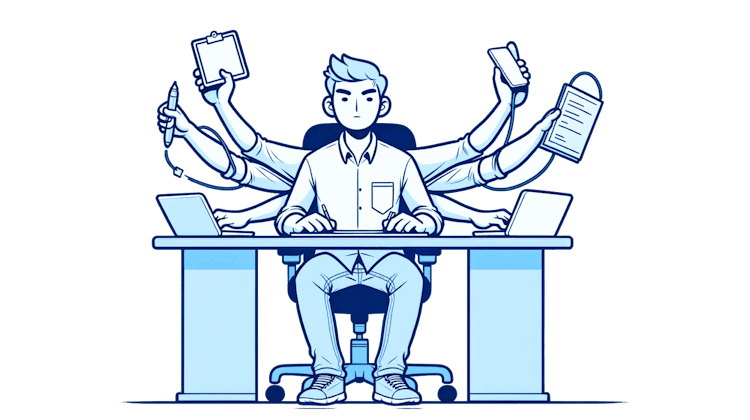
In today’s dynamic professional landscape, entrepreneurship increasingly attracts individuals who are already employed. Establishing a side business—often referred to as moonlighting or a side hustle—has become common practice.

However, starting a business while holding a full-time position involves legal, ethical, and practical challenges.
This article explores how to balance these dual roles while minimizing risk and maximizing long-term potential.
Legal Considerations and Employment Contracts
Before launching any business activity, carefully review your employment contract. Many agreements include:
Non-compete clauses
Confidentiality agreements
Restrictions on external work
These provisions may limit or prohibit certain entrepreneurial activities—especially if your business overlaps with your employer’s interests.

Always verify contractual restrictions before starting a business.
Ignoring non-compete or confidentiality clauses can result in legal disputes, termination, or financial penalties. Your business must remain clearly separate from your employer’s operations.
Beyond contracts, internal company policies may set expectations around external work. In the UK, intellectual property ownership often depends on whether work is created “in the course of employment,” as defined by your role and contract. Developing ideas outside working hours and without company resources helps demonstrate separation, but contractual terms remain decisive.
Managing Potential Conflicts of Interest
One of the biggest risks is a conflict of interest, which arises when your business:
Competes with your employer
Operates in the same market
Uses similar clients, suppliers, or know-how
Such conflicts can damage trust and lead to serious consequences. To reduce risk:
Maintain clear boundaries
Keep activities professionally distinct
Communicate openly and transparently where appropriate
Tax Obligations and Financial Management
Running a side business creates additional tax responsibilities.
In the UK, business income may need to be reported to HM Revenue and Customs (HMRC), depending on its level and nature. If your gross income from trading or casual business activities exceeds the annual trading allowance, you are generally required to register for Self Assessment and declare this income.
This may include:
Registering as a sole trader, forming a partnership, or incorporating a limited company
Submitting accurate and timely tax returns where required
Declaring all taxable income from both employment and business activities
When employment is combined with self-employment, National Insurance Contributions (NIC) can be more complex.
In 2025/26, most self-employed individuals do not pay Class 2 NIC directly, as it is treated as paid once profits reach the relevant threshold, with voluntary payments possible at lower profit levels. Most National Insurance for the self-employed is instead paid through Class 4 contributions, which apply once profits exceed the Lower Profits Limit. The exact position depends on profit levels and how the work is structured.
Key Financial Obligations
Register business activity with HMRC
Declare all sources of income
Track National Insurance Contributions
Separate personal and business finances
Practical Strategies for Balancing Both Roles
Successfully managing both roles requires strong time management. Begin by realistically assessing:
How many hours your business needs
Whether evenings and weekends are sufficient
How growth will impact your availability
Many entrepreneurs start small, then scale gradually.
Equally important is maintaining a healthy work–life balance. Overcommitment can strain health and relationships. Setting boundaries, prioritizing tasks, and delegating where possible are essential. Involving family members can also increase understanding and support.
Practical Time Management Tips
Block fixed weekly hours for your business
Define clear “no-work” personal time
Automate or outsource small tasks early
Financial Management and Investment
Early-stage financial discipline is critical. Rather than extracting profits immediately, many founders choose to reinvest earnings to support sustainable growth.
Best practices include:
Keeping a separate business bank account
Tracking expenses consistently
Building a financial buffer before scaling
This approach strengthens credibility with future partners or investors.

Real-Life Scenario
Jane, a full-time marketing manager, launched a boutique digital agency alongside her job. She:
Reviewed her employment contract carefully
Avoided overlap with her employer’s services
Communicated her plans transparently
Managed time through evenings and weekends
As her agency expanded, Jane transitioned to part-time employment, and eventually committed to her business full-time—successfully and without conflict.